How to Do Bank Reconciliation: A Step-by-Step Guide
Last Updated: 18 November, 2026
•
Palashy Mathur Content Writer
Analyst Recognition
HighRadius Named a Challenger in 2025 Gartner® Magic Quadrant™ for Financial Close and Consolidation Solutions
Discover how HighRadius brings practical, results-driven AI to record-to-report processes with automation, anomaly detection, and continuous close capabilities.
Business owners regularly compare their records with bank transactions to ensure there are no errors. It is a best practice that enables them to check that their balance sheet numbers are accurate and match the bank statement. If any discrepancies or fraudulent charges are identified, the required changes are made to the balance sheet.
Bank reconciliation is part of the month-end close process, which includes reviewing the company’s balance sheet, income, bank statements, expenses, intercompany trades, and other information. It is essential for maintaining accurate business financial records, which helps in tax filing and gives an overall idea of the company’s finances. The importance of bank reconciliation makes it essential for organizations to leverage a bank reconciliation software to ensure data accuracy while accelerating reconciliation timelines.
Key Takeaways
Bank reconciliation involves comparing a company’s accounting records with bank statements to identify discrepancies, missing transactions, duplicate entries, and potential errors.
Regular bank reconciliation helps maintain accurate cash balances, detect fraudulent activity, resolve discrepancies early, and support reliable financial reporting.
Automated bank reconciliation reduces manual effort, improves transaction matching accuracy, speeds up discrepancy detection, and helps finance teams manage growing transaction volumes.
What Does Reconciliation of Bank Statements Mean and Why Is It Important?
Bank statement reconciliation is the process of comparing a company’s accounting records with its bank statement to identify discrepancies, missing transactions, duplicate entries, or errors. Also known as bank reconciliation, it helps businesses maintain accurate cash balances, detect potential fraud, and identify errors before they affect financial reporting or cash flow decisions. As part of the financial close process, regular reconciliation supports reliable financial records.
Reconciliation is 30% faster with AI!
Save your team’s time for strategic financial oversight.
Companies may assign different individuals to handle specific aspects of bank reconciliation, depending on their transaction volumes and internal processes. Following a consistent sequence helps ensure that every transaction is accounted for. Here are 8 steps, in the right order of operations, that explain how to reconcile a bank statement:
1. Acquire bank statements
The first step is to obtain a detailed statement from the bank. Note the opening and closing bank balance, deposits and withdrawals, checks cleared and rejected by the bank, transaction charges, and bank fees or interest. These details provide the basis for comparing bank transactions with the company’s accounting records.
2. Aggregate business records
Next, prepare the business records, which can be maintained in accounting software or manually on a spreadsheet using a bank reconciliation template. Obtain the cash book or general ledger for the same reconciliation period and note the recorded opening and closing balances.
3. Match deposits and withdrawals to the balance sheet
Compare the deposits and withdrawals listed in the bank statement with those recorded in the company’s cash book or general ledger. Match each transaction by amount and date, and mark the entries that correspond. Note any unmatched transactions, including deposits in transit and outstanding checks, for further investigation.
4. Check income and expenses
Review the income and expenses recorded in the company’s accounting records against the bank statement. Identify any missing deposits, unrecorded payments, or differences in transaction amounts. This helps determine whether discrepancies result from timing differences, missing entries, or errors in recording financial transactions.
5. Identify errors with check deposits
Verify that all checks issued and deposited by the company are reflected correctly in the bank statement. Check for rejected or returned checks, uncleared checks, and discrepancies in check amounts. If a transaction has been incorrectly processed by the bank, contact the bank to investigate and resolve the issue.
6. Check for other transactions
Review other debit and credit entries, including bank fees, interest earned, direct debits, and automatic payments. These transactions may not have been recorded in the company’s accounting records when they occurred. Identify such entries and record the missing transactions in the cash book or general ledger.
7. Adjust balances
After identifying the discrepancies, make the necessary adjustments to reconcile the bank and book balances. Add unrecorded inflows, deduct unrecorded outflows, and adjust for internal errors in the company’s accounting records. Also, account for timing differences, such as deposits in transit and outstanding checks, when adjusting the bank balance.
8. Final check
Review the adjusted balances to ensure that the bank statement balance and the company’s book balance agree. Verify that all transactions have been accounted for and that outstanding discrepancies have been investigated. Performing transaction reconciliation helps confirm that individual entries are accurately matched and recorded. Repeat the review if any differences remain.
How Often Should You Reconcile Bank Statements?
The frequency of reconciling bank statements depends on the size and complexity of the business and its transaction volume. For larger companies with a high volume of transactions, it’s advisable to reconcile bank statements daily to ensure that any discrepancies or errors are promptly identified and corrected.
For smaller companies, it’s common to reconcile bank statements during the monthly or quarterly close process. However, there are situations where a bank reconciliation might be necessary at the earliest. For example, if a business identifies any suspicious activity or unidentifiable transactions, it’s essential to prepare a bank reconciliation immediately. Similarly, if customer payment checks on the balance sheet do not match bank records, a cross-check is necessary.
Ebooks
Every Second Spent on Manual Reconciliation Costs You Money
Discover the financial impact of automation on accounting accuracy and operational efficiency.
6 Common Errors to Avoid During Bank Reconciliation
Bank reconciliation can be prone to errors, particularly when transactions are recorded manually or reviewed inconsistently. Understanding these common mistakes can help businesses maintain accurate financial records and improve the reconciliation process.
1. Failing to record all transactions:
Not recording all transactions in the accounting system can lead to discrepancies between the company’s accounting records and the bank statement. Missing deposits, withdrawals, or other entries can result in inaccurate cash balances and incomplete reconciliation.
2. Recording transactions incorrectly:
Entering incorrect transaction amounts, dates, or descriptions in the accounting system can create discrepancies during reconciliation. Duplicate entries and transactions recorded in the wrong accounts can also affect the accuracy of financial records and make it difficult to match transactions.
3. Failing to account for bank fees and charges:
Bank fees, service charges, and other deductions may not be recorded in the company’s accounting records when they occur. Failing to account for these transactions during reconciliation can result in differences between the bank statement and the company’s cash balance.
10% of all occupational fraud cases in small businesses are due to bank account reconciliation errors.
Source: Association of Certified Fraud Examiners
4. Starting with an incorrect opening balance:
An incorrect opening balance can affect the entire reconciliation process. Before reconciling an account, verify that its opening balance matches the previous period’s closing balance and that all prior-period adjustments have been recorded correctly.
5. Failing to identify and resolve discrepancies:
Unmatched transactions and differences between bank and book balances must be investigated and resolved promptly. Leaving discrepancies unexplained can result in inaccurate financial records, unresolved accounting errors, and potential cash reporting issues.
6. Not reviewing reconciliation reports:
Reconciliation reports summarize matched transactions, outstanding items, and unresolved discrepancies. Failing to review these reports can allow errors to go unnoticed and make it difficult for reviewers to verify the accuracy and completeness of the reconciliation.
Avoiding these common errors helps maintain accurate financial records and supports informed business decisions. Regular reconciliation and review of financial records support fraud and error detection, helping businesses identify and resolve discrepancies promptly and reduce the risk of financial issues.
Ebooks
Is Your Bank Reconciliation Turning Out To Be A Bottleneck?
AI agents auto-match 95% of transactions, freeing teams to focus on actual anomalies.
Suppose a company has a cash book balance of $7,000 and a bank statement balance of $4,975. The difference arises from a $2,000 deposit in transit, a $25 unrecorded bank service fee, and a $4,000 outstanding check. After adjusting the book balance for the service fee and the bank balance for the deposit and outstanding check, both balances equal $6,975. This illustrates a basic bank reconciliation example.
Tips for Streamlining Your Bank Reconciliation Process
Following a consistent approach can make bank reconciliation more accurate and less time-consuming. Here are some best practices for reconciling bank statements and keeping your bank reconciliation process accurate:
1. Reconcile at least once every month
Make monthly reconciliation a habit by cross-checking bank account balances and bank statements with the company’s accounting records during the closing process. Regular bank reconciliation helps identify discrepancies early and prevent errors from accumulating. Businesses with high transaction volumes may need to reconcile their accounts more frequently.
2. Document the process
Maintain documentation of each reconciliation, including supporting documents, identified discrepancies, adjustments, and approvals. This creates an audit trail that helps finance teams investigate errors, review previous corrections, and provide management with accurate information when needed.
3. Record transactions immediately
Record transactions in the general ledger or subledger as soon as they occur. Timely recording reduces the chances of missing or duplicate entries and makes it easier to match transactions during reconciliation. Maintaining accurate source records also helps finance teams investigate discrepancies more efficiently.
4. Know that banks might also make errors
Not all reconciliation discrepancies originate within the company’s accounting records. Banks can also make errors, such as incorrect transaction amounts, duplicate charges, or missing deposits. If a discrepancy cannot be resolved internally, contact the bank to investigate and correct the error.
5. Standardize the workflow
Establish a consistent reconciliation workflow with clearly defined steps, responsibilities, and review procedures. Creating a checklist helps ensure that every account follows the same process. Businesses can also use reconciliation software or accounting software such as QuickBooks Online to organize and manage reconciliation activities.
6. Automate the process
Automating bank reconciliation reduces the time spent on manual transaction matching and minimizes the risk of human error. Account reconciliation software can compare transactions across different data sources, identify matching entries, and flag discrepancies for investigation. This allows finance teams to focus on unresolved items rather than routine manual checks.
Benefits of Automating Your Bank Reconciliation
Automating bank reconciliation helps businesses reduce manual effort, improve transaction matching accuracy, and identify discrepancies faster. It also improves productivity, supports better cash visibility, reduces processing costs, and makes reconciliation easier to scale as transaction volumes grow. These advantages highlight the broader benefits of automating reconciliation for finance teams.
How can HighRadius Help You with Bank Reconciliation?
Spending hours cleaning up exceptions, chasing unmatched items, and still relying on spreadsheets and rule-based tools means businesses are still firefighting while their legacy systems hold them back.
To help them accelerate the reconciliation process and ensure error-free financial close, HighRadius’s Record-to-Report software presents Agentic AI-led account reconciliation and bank reconciliation solutions that proactively match transactions, resolve exceptions, and post entries, even before the finance teams get involved. These solutions offer:
Automates certification, standardizes account formats, and ensures real-time visibility across entities. It auto-certifies low-risk accounts, eliminates offline trackers, and centralizes supporting documents. With built-in workflows and audit trails, teams close faster with fewer follow-ups.
Matches payroll transactions with clearing accounts and posts adjustments automatically. It detects mismatches between payroll runs and clearing entries with precision. Teams eliminate time spent reviewing spreadsheets or reclassifying balances manually.
Syncs GL and IMS data, flags variances, and posts corrections in real time. Agentic AI learns how your teams resolve recurring mismatches across entities. No more back-and-forth emails or month-end reconciliation bottlenecks between divisions.
Auto-matches daily credit card transactions to bank statements and flags mismatches instantly. It identifies duplicates, partial matches, or unposted items automatically. Exception volumes drop significantly, and reconciliations happen without delays.
Creates, validates, and posts journal entries with zero spreadsheet dependency. AI determines accrual logic based on historical behavior and policy settings. The result: cleaner records, fewer manual postings, and faster period-end closes.
Auto-calculates adjustments, classifies them, and posts allowance journals. It handles complexities in billing schedules, prepayments, and revenue recognition. No need for offline models—everything is traceable and audit-ready in one place.
Agentic AI in account reconciliation clears bottlenecks, not just flags them—helping finance teams reduce manual work and unlock 99% reconciliation accuracy.
Take a deep dive into HighRadius’ R2R solutions
Getting granular visibility and control into your accounting process is just a click away.
Achieve up to 90% transaction auto-match with out-of-the-box matching rules
Financial Close Management
Reduce days to close by 30% with a detailed checklist for month-end close
Frequently Asked Questions (FAQs)
1. How do you prepare a bank reconciliation statement?
To prepare a bank reconciliation statement, compare the closing balance in the bank statement with the cash balance in the company’s accounting records. Identify differences such as outstanding checks, deposits in transit, bank fees, or errors. Make the necessary adjustments and verify that the adjusted balances match.
2. What are the two items used to reconcile a bank account?
The two primary documents used for bank reconciliation are the bank statement and the company’s cash book or general ledger. The bank statement records transactions processed by the bank, while the company’s records show transactions recorded internally. Comparing both helps identify discrepancies and verify the accuracy of cash balances.
3. What are the four common reconciliation adjustments?
Four common reconciling items are deposits in transit, outstanding checks, bank service charges, and interest earned. Deposits in transit and outstanding checks account for timing differences between bank and book balances. Bank charges and interest earned may require adjustments to the company’s accounting records if they have not been recorded.
4. How to manually reconcile a bank statement?
To manually reconcile a bank statement, obtain the bank statement and the company’s cash records for the same period. Compare each deposit and withdrawal, mark matching transactions, and identify unmatched entries. Investigate discrepancies, record missing transactions, adjust the relevant balances, and verify that the adjusted balances agree.
5. How often should you reconcile your bank account?
Bank accounts should generally be reconciled monthly as part of the financial close process. However, businesses with high transaction volumes may need to reconcile their accounts daily or weekly to identify discrepancies promptly. Any suspicious or unidentified transactions should be investigated as soon as they are detected.
6. What causes discrepancies in bank reconciliation?
Discrepancies in bank reconciliation can result from timing differences, such as outstanding checks and deposits in transit, or errors in recording transactions. Missing entries, duplicate transactions, incorrect amounts, unrecorded bank fees, and bank processing errors can also cause differences between the bank statement and the company’s accounting records.
Resource Library
Resource Hub
ASSETS
Cash Flow Calculator (FREE)
Track operating and net cash flow while forecasting balances to maintain liquidity and financial control.
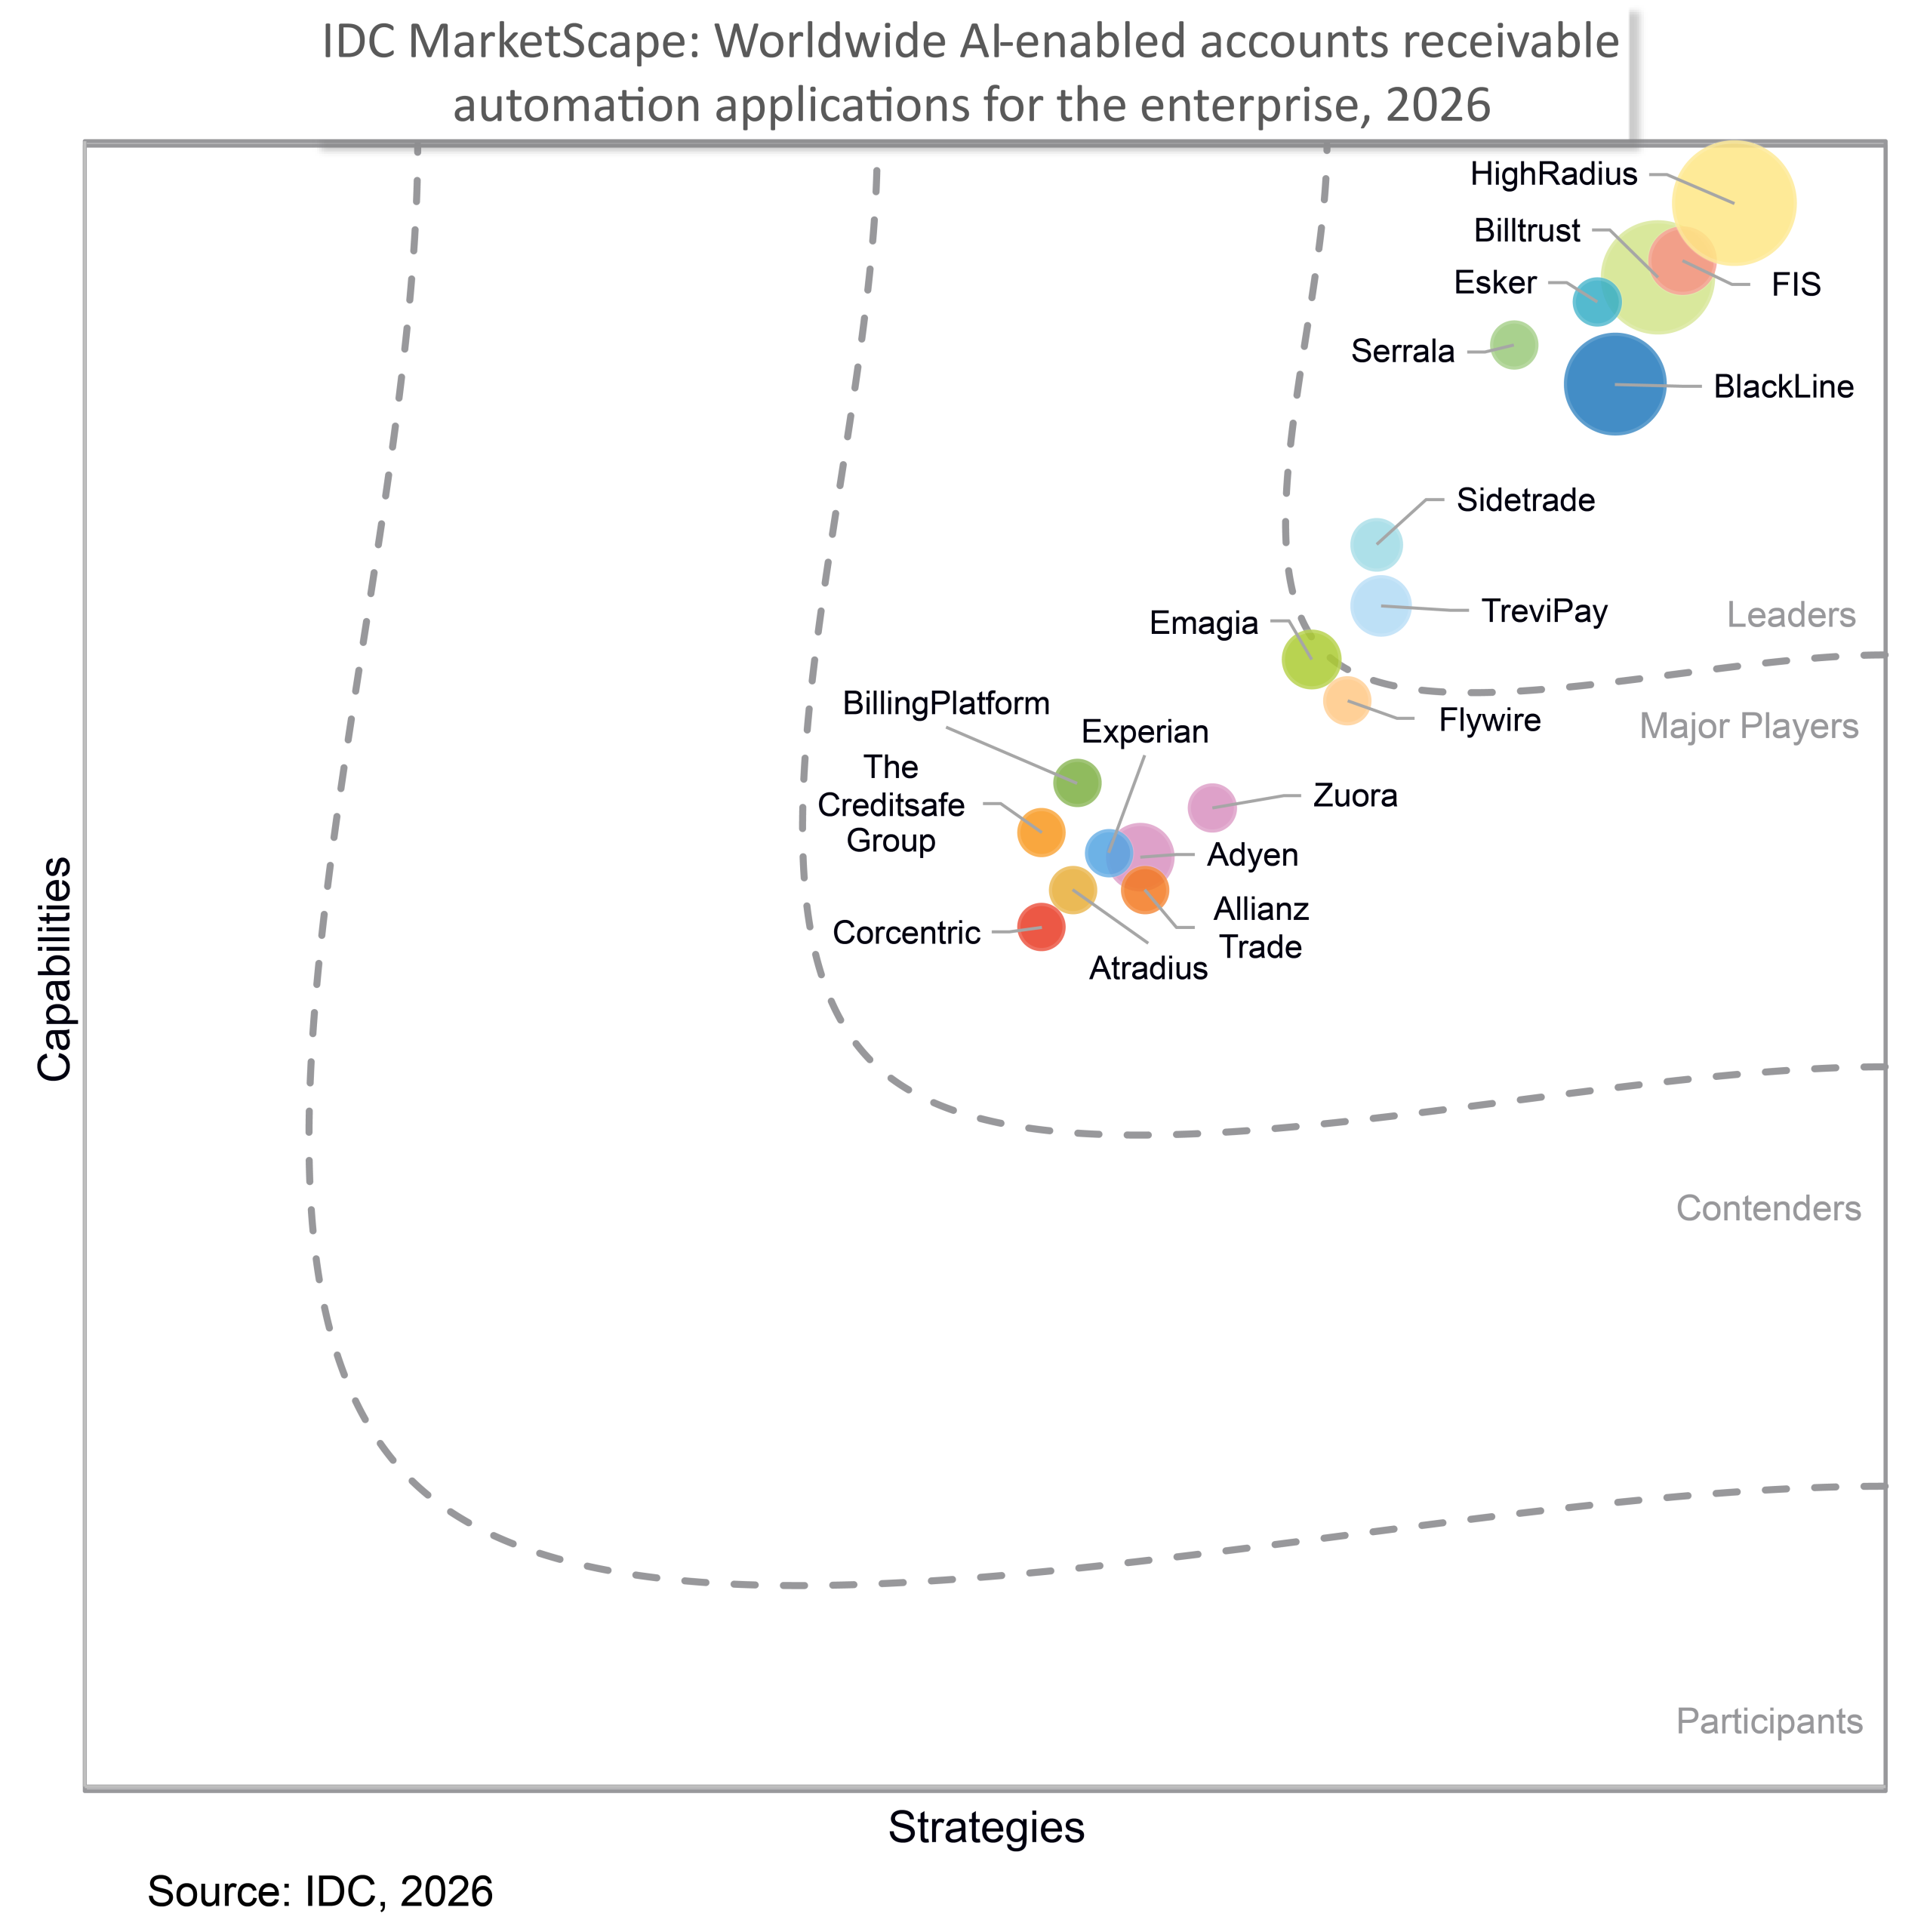
HighRadius recognized as a "Leader" in IDC Marketscape: Worldwide AI-enabled accounts receivable automation applications for the enterprise 2026 vendor assessment
Recognized as a Leader in 2026 Vendor Assessment for unifying credit, collections, cash application, deductions, e-invoicing, and payments on one AI platform to advance enterprise-wide invoice-to-cash transformation.
Forrester Recognizes HighRadius in The AR Invoice Automation Landscape Report, Q1 2023
Forrester acknowledges HighRadius’ significant contribution to the industry, particularly for large enterprises in North America and EMEA, reinforcing its position as the sole vendor that comprehensively meets the complex needs of this segment.