Modern B2B payments software increasingly supports eChecks, the electronic evolution of the traditional paper check because they offer a secure, cost-effective way to move funds without paper, postage, or manual processing. Processed over the ACH network, eChecks let businesses debit and credit bank accounts electronically, speeding up collections, reducing processing costs, and improving reconciliation when integrated with accounting systems. For finance teams managing recurring invoices or high-value transfers, adopting eChecks through an automated payments platform can cut errors, enhance cash-flow visibility, and lower merchant fees compared with card-based payments.
What Is an eCheck or Electronic Check?
An eCheck, or electronic check, is like a digital version of a paper check. It’s a way to pay from your checking account without paper. Instead of a paper check, you share your bank details and payment info using a form. This gets your payment ready to go electronically.
eChecks play a pivotal role by modernizing payment methods, replacing paper checks with efficient digital transactions, and enhancing financial accessibility and speed. This transformation streamlines interactions for individuals and businesses alike.

How are eChecks Different from Paper Checks?
In the financial landscape, you’ll often come across these two terms: eChecks and paper checks. In both methods, money is directly drawn from the payer’s account and deposited into the payee’s account.
e Checks and paper checks differ from each other in the method of transaction. While eChecks are digital and involve sharing payment details electronically, paper checks are physical documents filled out by hand.
Let’s take a look at an overview of the differences between eChecks and paper checks:
eChecks streamline processes with speed and convenience, whereas paper checks require manual handling and processing. Still, people often prefer using paper checks because of their familiarity with them. Both these payment methods can coexist with each other and can be used depending on the convenience of the payee.

Key Differences Between eChecks & Paper Checks
|
eChecks |
Paper Checks |
|
Sent and received electronically, its data is stored within a computer system |
A personalized piece of paper in a book format with issuer and user info |
|
Secure with multi-layered protection |
Carries risk of theft or loss |
|
Lower costs due to lower user charges, minimal printing and transit costs |
Involves higher charges due to increased printing, handling, and transit costs |
|
Lower processing time and amount can be transferred instantly |
Paper checks processing time is higher due to time taken for courier and actual processing by the bank |
|
Nothing needs to be carried. |
Must carry the checkbook with you. |
How Does an eCheck Work?
Let’s understand how electronicchecks work. As the name suggests, eChecks, or electronic checks are processed electronically. Money is electronically withdrawn from the payer’s checking account, transmitted via the ACH (Automated Clearing House) network, and deposited into the payee’s checking account.
E-checks reach their destination faster compared to traditional paper checks, as paper checks involve added logistical steps for successful payment. With paper checks, the recipient’s bank verifies the check and then sends it to the originating bank for verification and this process normally takes time to complete.
E-check processing is swifter, but it relies on the same information. The person initiating the electronic check payment must provide their bank routing number, account number, email address, and authorization.
Processing an electronic check involves four key steps:

How does eCheck payment processing work?
- Obtain authorization
Before a transaction can proceed, the company needs permission from the customer. This can happen through an online payment form, a signed order form, or even over the phone.
- Payment setup
After receiving approval, the company enters payment details into its online payment processing software.
- Finalize and submit
The company saves or submits the payment details in the software. This marks the beginning of the ACH transaction process.
- Confirmation and depositing funds
The payment is automatically taken from the customer’s bank account. The online system then provides the customer with a payment receipt, and the payment amount is deposited into the company’s bank account.
Typically, within one to three business days after initiating the ACH transaction, the funds arrive in the merchant’s bank account.
What are the Benefits of eChecks?
Now that we have learnt about the eCheck payment processing, let us explore the various benefits offered by eCheck payment processing.

- Simplified Digital Transactions: eChecks streamline online payments, eliminating the hassle of physical checks and enabling swift and secure transactions.
- Global Reach: eChecks transcend geographical boundaries, facilitating payments worldwide with ease and efficiency.
- Integration with Internal Financial Software: Seamlessly connect eCheck transactions with internal financial systems, optimizing record-keeping and enhancing organizational efficiency.
- Error Reduction: Automated processing minimizes human error, ensuring accuracy and reliability in financial transactions.
- Easy to Monitor: Real-time tracking capabilities empower users to monitor eCheck transactions effortlessly, enhancing transparency and control.
- Enhanced Process Efficiency: eChecks streamline payment workflows, reducing administrative burdens and increasing overall operational efficiency.
- Cost-Effective: Compared to traditional payment methods, eChecks offer significant cost savings, with lower transaction fees and reduced administrative expenses.

What are the Problems with eChecks?
Even as eChecks offers various benefits, there are a few potential challenges.
- One of the significant challenges is processing delays and errors. eChecks are subject to stringent processing deadlines and processes because they are processed via the ACH network. Payments may be refused or delayed if any information needs to be completed or accurate, which can annoy Customers and businesses.
- Another major drawback of an eCheck payment is the acceptance. Most merchant service providers prefer credit or debit card payments rather than eChecks.
- eCheck, like any other electronic payment, is subject to fraudulent risk. Customers should make sure that they only share their bank details to trusted merchants and keep a tight eye on their accounts to ensure no fraudulent transactions are occurring.
However, the benefits offered by eChecks far exceed the potential challenges. If your business often receives large credit card payments and wants to increase recurring payments while reducing merchant fees, consider accepting eCheck payments.
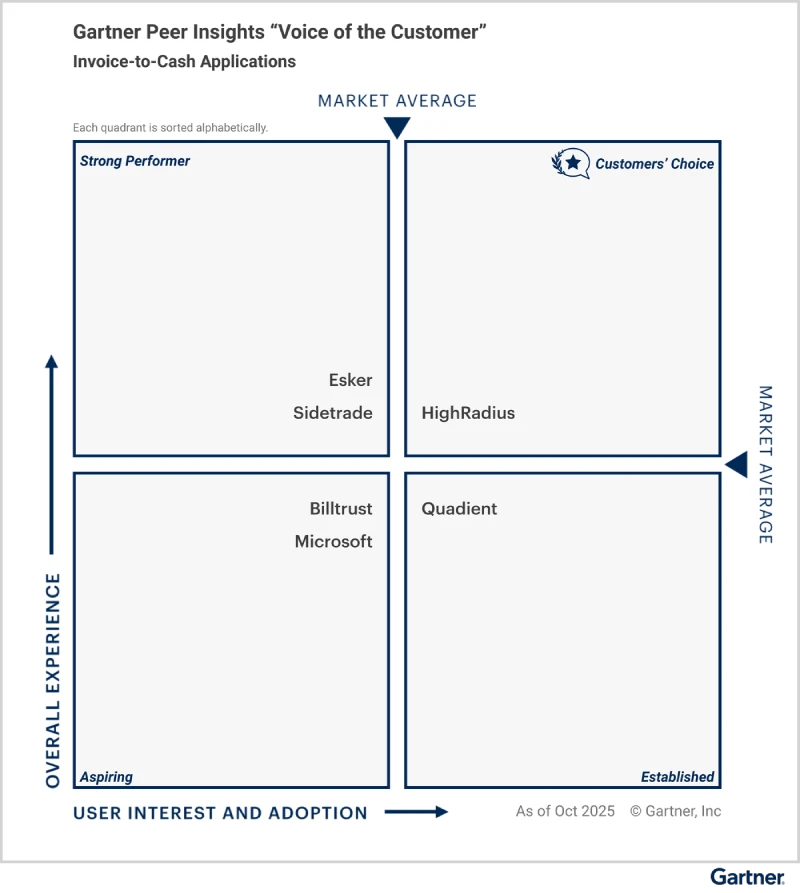
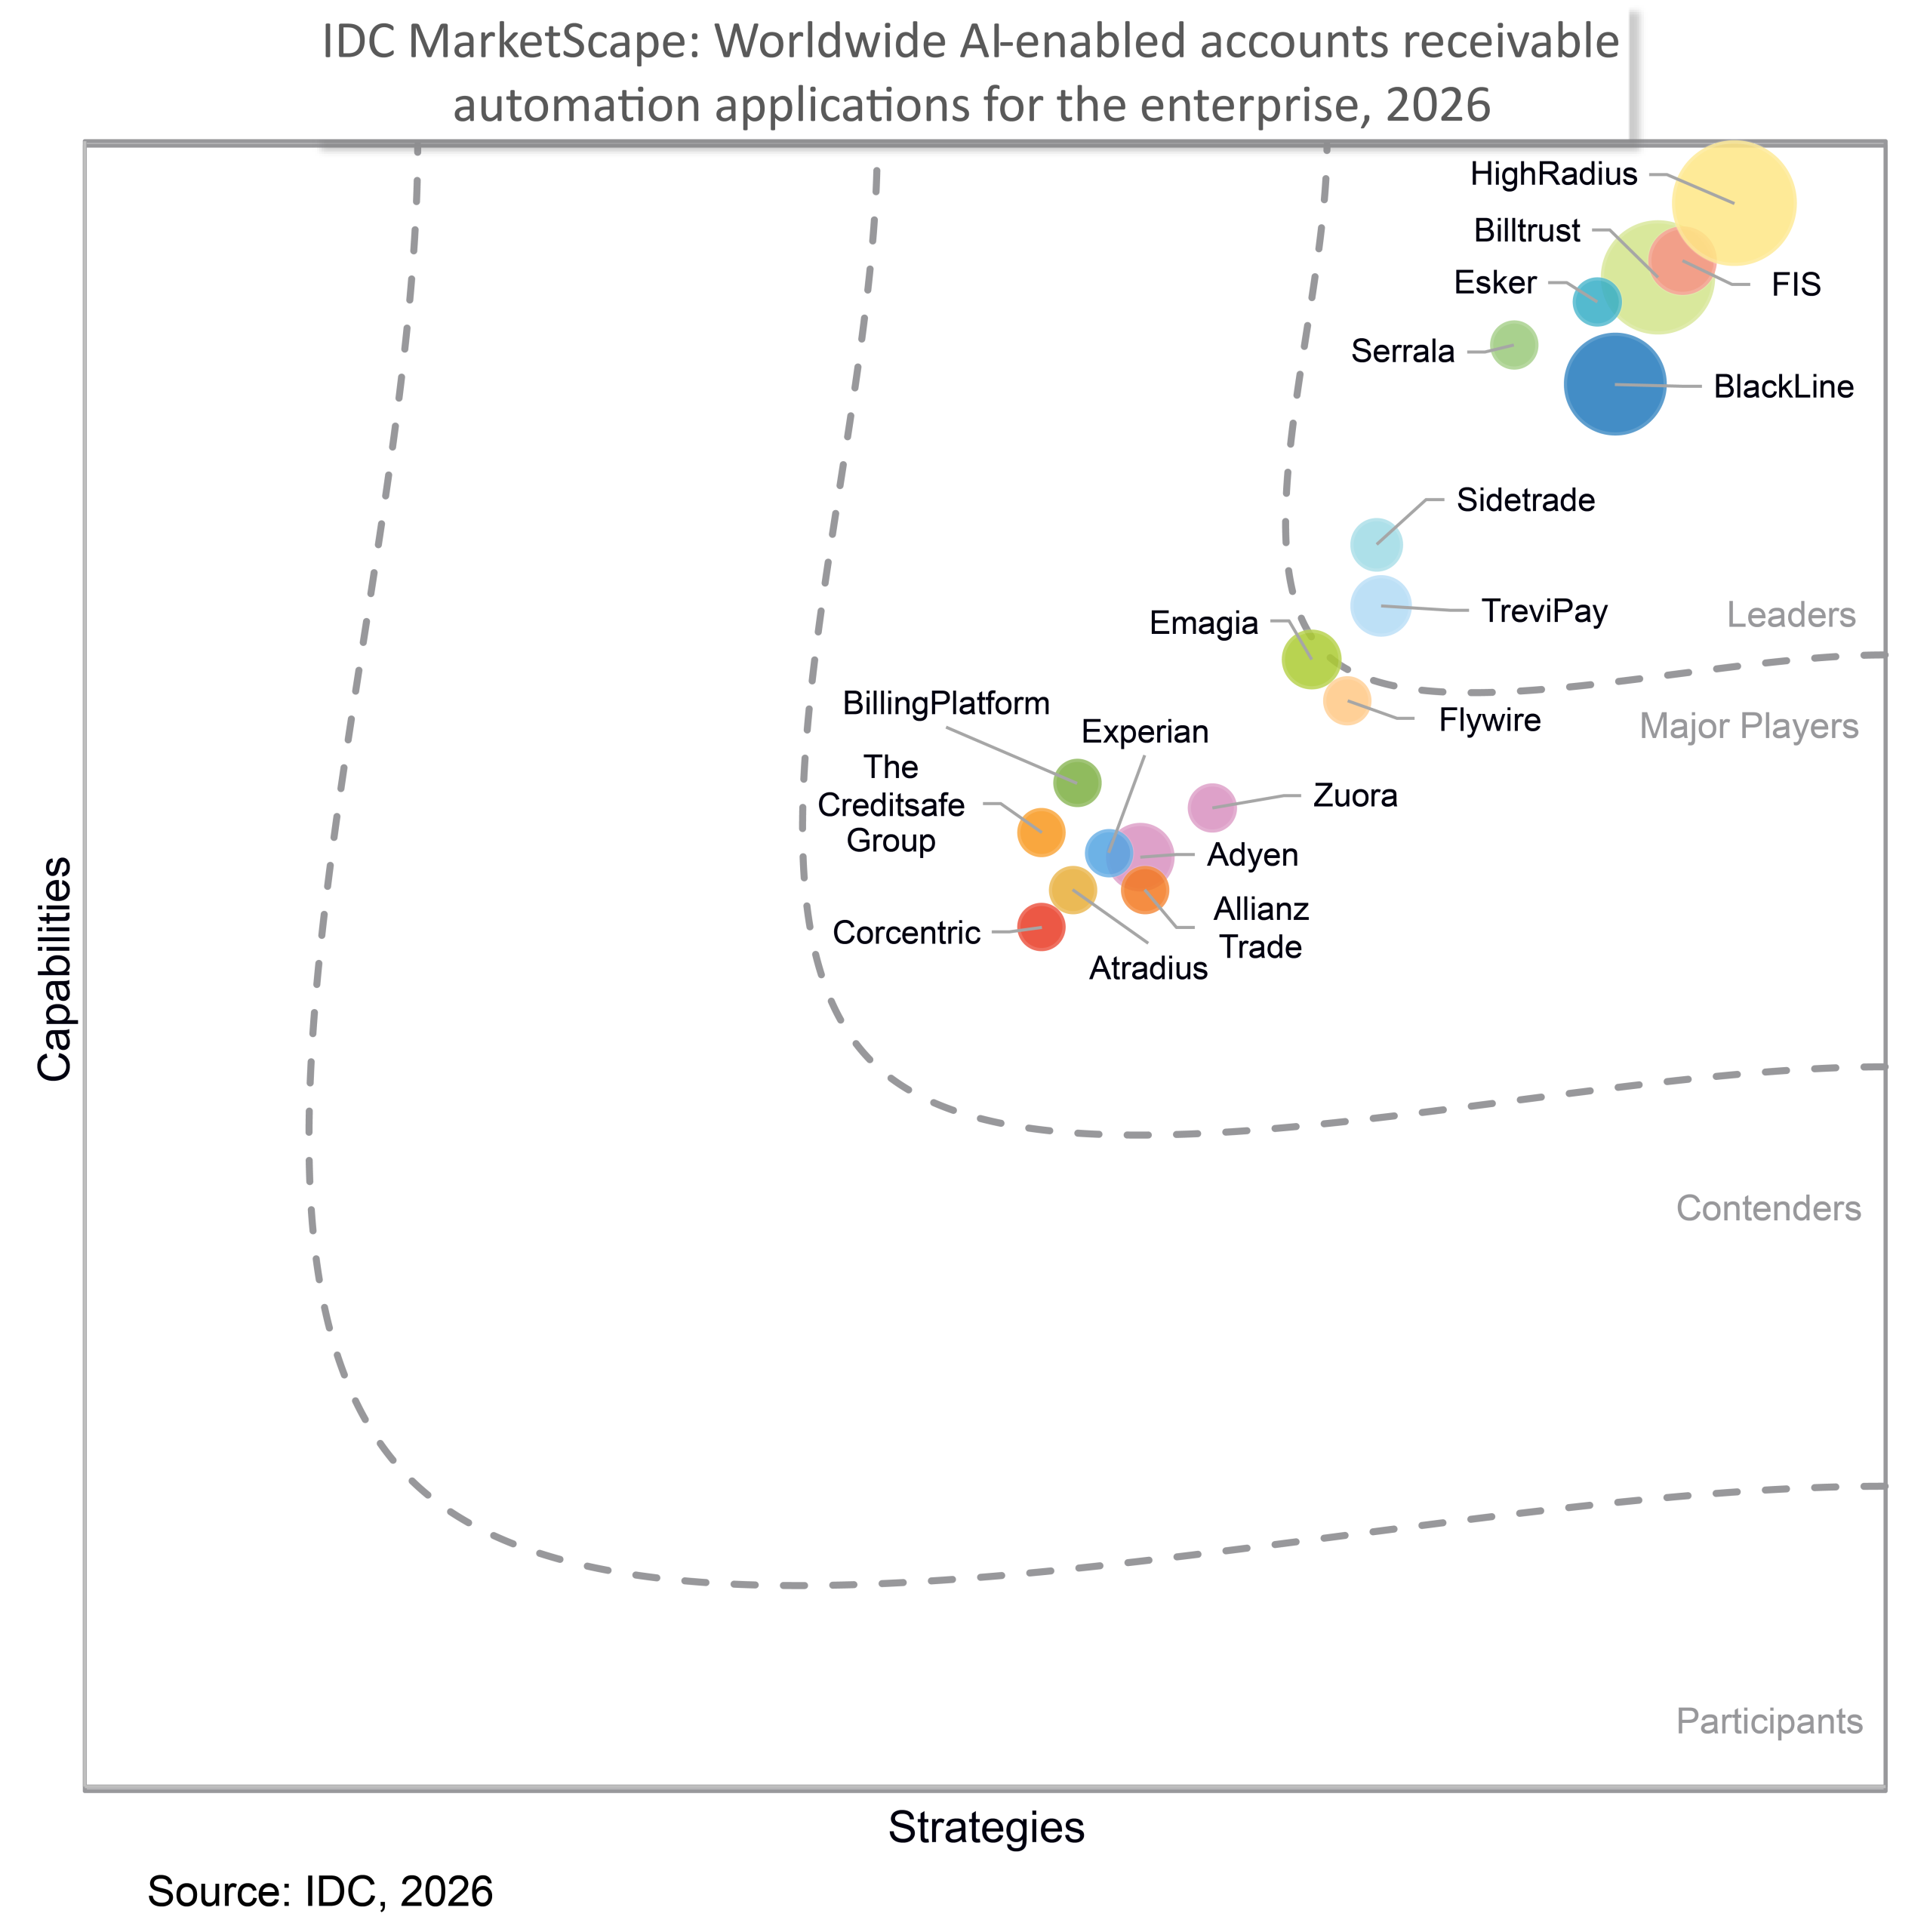
How can HighRadius B2B payments revolutionize your eCheck payment processing?
HighRadius B2B Payments revolutionizes eCheck processing with its extensive suite. Order to Cash, Treasury & Risk, and Record to Report Suites are all easily integrated with the suite’s stand-alone payments module. eCheck transactions are safe, quick, and economical thanks to essential components, including Interchange Fee Optimizer, Surcharge Management, and Payment Gateway.
The Payment Gateway enables the safe processing of various payment methods, including credit cards and ACH, and includes features like tokenization for enhanced security. Surcharge management ensures compliance and accurate surcharge calculation while offering flexibility regarding payment alternatives. Interchange Fee Optimizer minimizes merchant fees by optimizing transaction data and supporting multiple payment processors.
Integration with SAP extends payment workflows and enables sales orders and invoices to be processed efficiently inside the SAP system. The portfolio’s tokenization and data interception solutions reduce PCI compliance costs while enhancing security. Bank-to-bank transactions are accelerated by processing ACH/eChecks, improving cash flow, and reducing fraud risk.
The HighRadius B2B Payments Suite offers noteworthy benefits such as a 90% decrease in card processing expenses, reduced buyer friction, secure payment data handling, improved working capital, and increased processing efficiency. Phased deployments ensure speed to value and allow businesses to gradually implement complex payment functions that align with their needs and business units. HighRadius B2B Payments simplifies, secures, and streamlines financial transactions by offering companies eCheck processing solutions.