Soumi specializes in O2C, finance, and accounting transformation with a focus on bringing a domain-led perspective to accounting, finance and order-to-cash transformation. She crafts insight-driven, CFO-aligned content that helps finance teams optimize operational workflows and drive measurable outcomes. Beyond her professional work, Soumi is a published author of two books, a poetess, an avid reader, and a storyteller who enjoys exploring narratives across both B2B and creative formats.
2026 Automation Benchmark Report
HighRadius 2026 Automation Benchmark Report For The Office Of The CFO
Understand if your performance is on par with top 10% of the organizations. Identify gaps, best practices and know how you can drive value through Agentic AI-Driven Automation.
Assess creditworthiness using multiple data points: Evaluate credit reports, financial statements, payment history, debt levels, trade references, and financial ratios to build a comprehensive view of customer risk.
Standardize and automate credit assessments: Use credit applications, automated credit report extraction, credit agency integrations, and scoring models to improve assessment efficiency and consistency.
Monitor customer risk continuously: Track payment behavior, credit agency alerts, financial updates, and changing risk indicators to identify potential defaults early and adjust credit decisions proactively.
Every sale made on credit carries a silent question—will you get paid on time? For many businesses, this uncertainty directly impacts cash flow and growth. In fact, 82% of business failures are tied to poor cash flow management, often driven by delayed or missed payments (U.S. Bank study). This is where creditworthiness becomes essential—not just as a financial check, but as a strategic tool to protect revenue and reduce risk.
Understanding a customer’s creditworthiness helps you decide who to extend credit to, how much to offer, and under what terms. By evaluating financial stability, payment behavior, and risk indicators, businesses can avoid costly mistakes. So, how can you accurately assess creditworthiness and make confident credit decisions? Let’s break it down.
Find the best-fit credit management solution with our Vendor Evaluation Scorecard
Use a Fortune 500–inspired checklist covering 66 must-have parameters for stronger creditworthiness assessment.
Creditworthiness refers to the process of evaluating how likely a customer will default on their payment obligations. It is critical for businesses as it helps assess customers’ financial reliability before deciding on payment terms and determining whether they should be allowed to purchase on credit.
Assessing a company’s creditworthiness relies on two factors. One is measured by a customer’s credit score, a three-digit number based on the insights in their credit report. A high credit score means a customer’s creditworthiness is high, and vice versa. The second factor involves payment history. Your business won’t like to extend credit to a customer who shows delayed or missed payments or financial instability.
Why Assessing Customer’s Creditworthiness Is Crucial?
Assessing business creditworthiness helps you gauge the credit risk when selling on credit, guiding your decisions on whether to extend credit and under what terms. A good credit score allows for more flexible payment terms, while a poor score signals financial instability, prompting stricter terms to protect cash flow and reduce bad debts. Creditworthiness is essential because it:
Gauges the risk of extending credit, safeguarding against financial losses from missed or late payments.
Manages cash flows by predicting payment timelines and minimizing delays.
Tailors credit terms and limits to balance competitive offers with financial security.
What Are The Factors Determining Creditworthiness?
Numerous factors determine a customer’s creditworthiness, including payment history, debt levels and credit utilization, credit history, credit management trends, financial statements, trade references, etc. As customer’s business cash flow improve, they can more effectively manage their credit and ensure timely payments.
Credit history reflects how a customer has managed their credit in the past. A history of timely payments generally indicates a lower risk and helps build a strong customers’ business credit report.
Financial statements to assess your customer’s overall financial health, profitability.
Credit scores like FICO or Vantage Score to check if customers have a higher credit score. It means they have a lower risk of non-payment and greater creditworthiness.
Debt levels and credit utilization helps check if existing debt or credit is being paid and how well a customer can handle new debt or credit in the current financial situation.
Trade references to gather insights from other businesses that have previously extended credit to the customer and get practical feedback on a customer’s payment history.
Payment history to find out if a customer is able to settle financial obligations and is trustworthy and capable of managing new credit.
Key Factors to Evaluate Customer Creditworthiness
Factor
What to Check
Red Flag
Credit history
Length and conduct of credit relationships
Recent defaults or write-offs
Financial statements
Cash flow, income, and balance sheet strength
Negative cash flow or rising leverage
Credit score/rating
Credit bureau scores, such as D&B PAYDEX
Score below internal policy threshold
Debt levels and utilization
Existing obligations relative to repayment capacity
High utilization or overextension
Trade references
Payment behavior reported by other suppliers
Slow or missed payments
Payment history
Track record of timely payments
Repeated late payments
How To Determine Creditworthiness Of A Customer?
Before granting credit, a company should assess the customer’s competence to manage and repay outstanding debts. Here are six ways to determine the creditworthiness of a potential customer. The same steps apply when you evaluate subcontractor creditworthiness, with added checks on licenses, insurance, bonding, and trade references from other contractors
1. Collect relevant details to extend credit
Before extending credit, it’s crucial to ask customers to complete a business credit application form, which includes general business information, bank references, credit history, and more. These details help consolidate client data, expediting the customer onboarding process. For small or newly formed businesses, also review the owner’s personal credit report, as it often shows how the business is likely to pay.
2. Check credit reports
A credit report builds a customer’s credit profile, with information on the company and its financials, enabling you to generate credit scores. Credit reports of a company are available for purchase from credit reporting agencies such as Experian, D&B, and Equifax.
Standardize credit applicationS with our Business Credit Application Template
The financial report of a company provides insights into financial statement analysis and its cash position. Financial reports include the cash flow statement, income statement, and the balance sheet of the company. The financial health of a new customer should be examined thoroughly by reviewing their public financial statements.
4. Evaluate the debt-to-income ratio
Another way to evaluate the business credit risk of a customer is by examining their debt-to-income ratio. This ratio provides insights into how much of their monthly income is allocated towards debt repayment. Calculate the ratio by dividing monthly debt payments by gross monthly income. A low DTI ratio indicates a healthy balance between debt and income, whereas a high DTI ratio shows that a client has more obligations than the monthly income.
Debt-to-income ratio = Total monthly debt payments/Gross monthly income
5. Conduct credit investigation
You must use multiple sources to conduct further investigations to evaluate the business credit risk of a customer. These investigations usually includes checking:
Customer background and history
Credit policies
Accounts receivable aging report
Economic and political climate analysis
Future business probability
To check the creditworthiness of an international customer, use local credit agencies such as Graydon or Crefo alongside D&B, ask for audited financial statements, and review country risk and payment currency before setting terms.
6. Perform credit analysis
The last step is to get a comprehensive credit analysis of the customer accounts. Evaluate all trade references and apply credit analysis to predict the probability of default. Consider key financial metrics like profitability ratio, leverage ratio, and liquidity ratio.
Assessing a customer’s creditworthiness should not end with the initial approval; a modern B2B credit decisioning framework also considers how payment behavior and exposure change throughout the customer relationship.
How to Extend Credit to a Higher-Risk Customer
When a customer presents elevated credit risk but offers business value, credit teams may choose to extend credit with additional safeguards. The objective is to balance customer growth opportunities with controlled credit exposure. Consider the following approaches:
1. Set a Lower Initial Credit Limit
Start with a conservative credit limit based on the customer’s financial position, payment history, and available credit information. You may increase the limit as the customer establishes a consistent record of timely payments.
2. Tighten the Payment Terms
Consider shorter payment terms, partial prepayments, or deposits before shipment to reduce outstanding exposure. The terms should reflect the customer’s risk profile while remaining commercially viable.
3. Request a Personal Guarantee or Security
For appropriate business arrangements, you may request a parent company guarantee, personal guarantee, letter of credit, or other acceptable security. These provide additional recourse if the customer fails to meet payment obligations. The suitability and enforceability of such arrangements should be assessed based on the transaction and applicable legal requirements.
4. Stage Credit Availability
Instead of extending the full requested credit amount immediately, release credit in stages tied to order completion or agreed payment milestones. This allows the credit team to assess payment behavior before increasing exposure.
5. Monitor the Account More Frequently
Place higher-risk accounts on a shorter credit review cycle. Track payment delays, changes in financial condition, credit bureau updates, and utilization levels to identify emerging risks and reassess credit limits when necessary.
How To Monitor Creditworthiness?
The best way to monitor creditworthiness is to automate the data gathering process in your credit cloud. A robust and automated credit application software helps integrate with credit agencies and extract credit reports, provide real-time risk alert monitoring, aggregate public financials, provide credit scoring algorithms, etc. Beyond agency data, review account behavior in your own AR data, such as days beyond terms, partial payments, disputes, and changes in order patterns, to spot early signs of credit risk
Automate credit report gathering
A good credit management software automates the gathering of credit reports from 35+ agencies like D&B, Experian, Equifax, CreditSafe, Graydon, etc. through robust credit agency integrations You can also maintain subscriptions with multiple agencies of your choice as the best provider may vary from region to region and industry to industry.
For instance, it’s not possible to review a large national builder and a small contractor in the construction industry. While D&B will have good data on the national builder, it may not have nuanced reports on the small company. The CEO of a small construction company may use his/her own personal guarantee. Here, you would need to opt Experian to get the consumer rating on the CEO’s financial health.
Select the right credit management vendor with our Credit Management Vendor Evaluation Scorecard
Features like automated credit review and decision solution helps you gain granular data from over 100 data points from a credit report. Each report contains multiple data points depending on the subscription. You can use a subset of these data points in their credit scoring algorithms.
For example, ‘Paydex’ is a score that is calculated by D&B based on a customer’s past payment performance. It is very similar to a FICO score used to evaluate a customer’s payment behavior. This value will be automatically captured by credit application software for you to use in credit scoring algorithms.
Get real-time risk alerts
Automating credit reviewing will help you continuously monitor any risk alerts or notifications from credit agencies and news sources. Your credit cloud will proactively monitor sources to identify upcoming major activities such as bankruptcy, merger & acquisition, etc.
For example, Bloomberg publishes an article about Company A acquiring Company B. This news gets picked up by the monitoring to trigger a credit evaluation of Company A and B as they are both your customers.
Gather public financial data
You can automate the extraction of financial statements from 15+ public sources like Edgar, S&P, BvD, Crefo, Graydon, etc. Public companies are required to publish your financials regularly. Leverage this data to get better insights into creditworthiness than relying solely on credit agencies.
Similarly, you must derive financial ratios by letting your automated credit cloud calculate key ratios like Debt to Equity, Debt to Income, Current Ratio from the raw data points extracted from the financial documents. These derived ratios will further help assess your customer’s liquidity and get crucial inputs for credit scoring models.
Connectivity with trade associations
Automated credit application software gives you out-of-the-box integrations with 10+ trade associations across various industries, including the national chemical credit association (NCCA), National Association of Credit Management (NACM), etc. Additionally, ensure to leverage granular data points from these information like Historical aging, Credit Limit Utilization from other members of the Trade Association, shared anonymously.
What are the 23 SMART collection goals that your team must strive to achieve?
Get Accurate Creditworthiness Analysis with HighRadius Credit Management Software
How HighRadius Credit Management Solution Helps Accelerate Credit Decisioning
HighRadius Credit Management helps finance teams automate credit decisioning, standardize risk evaluation, and gain real-time visibility into customer exposure. By combining AI-driven scoring with automated workflows, it enables faster approvals, reduces manual effort, and improves control over credit risk.
With real-time credit risk analysis software and credit decisioning software, you can receive alerts for any changes in your customers’ credit profile and make data-driven credit decisions from unlimited credit reports. Our software integrates with your ERP system and can start monitoring your customers in just 30 days.
We offer configurable credit scoring AI software and approval workflows that can be customized based on geography, customer segments, business units, and other factors. You can fast-track credit approvals through complex corporate hierarchies, making the credit application process more efficient and streamlined.
Our highly configurable online credit application allows you to onboard customers across the globe with multi-language, customized credit applications embedded on your website. You can automatically capture financials, personal guarantees, and check bank references, reducing the need for manual data entry.
Our software also automatically extracts credit data from over 40+ global and local agencies, including credit ratings, financials, and credit insurance information. You can configure the auto-extracted data in your preferred currency, making it easier to analyze and interpret.
With AI blocked order management, you can auto-predict blocked orders based on the customers’ credit limit utilization and payment history. You can leverage AI-based release or partial payment recommendations for faster credit decisions, reducing the need for manual intervention.
Struggling With Incomplete Credit Applications?
Explore the #1 software that makes onboarding customer faster and easier
Accelerate payment recovery from delinquent customers and boost cash flow through automated collection workflows.
Cash App
Achieve same day cash application with automated remittance aggregation
Credit
Mitigate credit risk, reduce bad debt, and streamline customer onboarding with AI-powered insights.
Deductions
Reduce Revenue Leakage with AI Prediction models that identify valid and invalid deductions.
Online Credit Application
Onboard customers seamlessly with a configurable online credit application. Cut down on back-and-forth and collect all customer details in one go.
Frequently Asked Questions (FAQs)
1. How do you measure a company’s credit risk?
Measuring a company’s credit risk involves evaluating its financial health, reading financial statements, and gathering data from credit history, credit reports, and industry trends. Key indicators like credit rating, debt-to-equity ratio, and payment history are analyzed to assess the likelihood of default.
2. What is the best measure of creditworthiness?
The best measure of creditworthiness is a thorough evaluation of the five Cs of credit: character, capacity, capital, collateral, and conditions. Considering these factors provides a comprehensive understanding of an individual or company’s creditworthiness, aiding lenders in making informed decisions.
3. What are the 5 C’s of creditworthiness?
The 5 Cs of credit risk analysis are Character, Capacity, Capital, Collateral, and Conditions. These components help businesses assess a customer’s creditworthiness by evaluating factors such as the customer’s reputation, ability to repay, financial assets, collateral offered, and the broader economic conditions that may impact payment reliability.
4. What are the main benefits of creditworthiness?
A strong creditworthiness or higher credit scores can help you:
Establish credibility with suppliers and stakeholders
Negotiate better payment terms with suppliers
Stay competitive in the market
Qualify for larger loan amounts
Support major expenditures for business expansion
Strengthen relationships with suppliers
5. How to improve creditworthiness?
Here are a few things that will help improve creditworthiness:
Maintain accurate financial records
Enhance credit reporting practices
Strengthen financial management
Build strong relationships with credit partners
Optimize credit management process
Leverage credit insurance and guarantees
6. What is the difference between creditworthiness and credit score?
Creditworthiness is an overall assessment of a customer’s ability and willingness to repay debts, based on financial health, payment history, and existing obligations. A credit score is a numerical indicator used as one input in evaluating that creditworthiness.
7. How do suppliers/sellers assess creditworthiness?
Suppliers assess customer creditworthiness by reviewing credit reports, financial statements, payment history, debt levels, credit scores, and trade references. They may also evaluate cash flow and existing obligations to determine appropriate credit limits and payment terms.
Resource Library
Resource Hub
Order to Cash
Order to Cash software data sheet
Disconnected workflows can leave teams chasing data, while automated O2C has delivered 20% lower past dues.
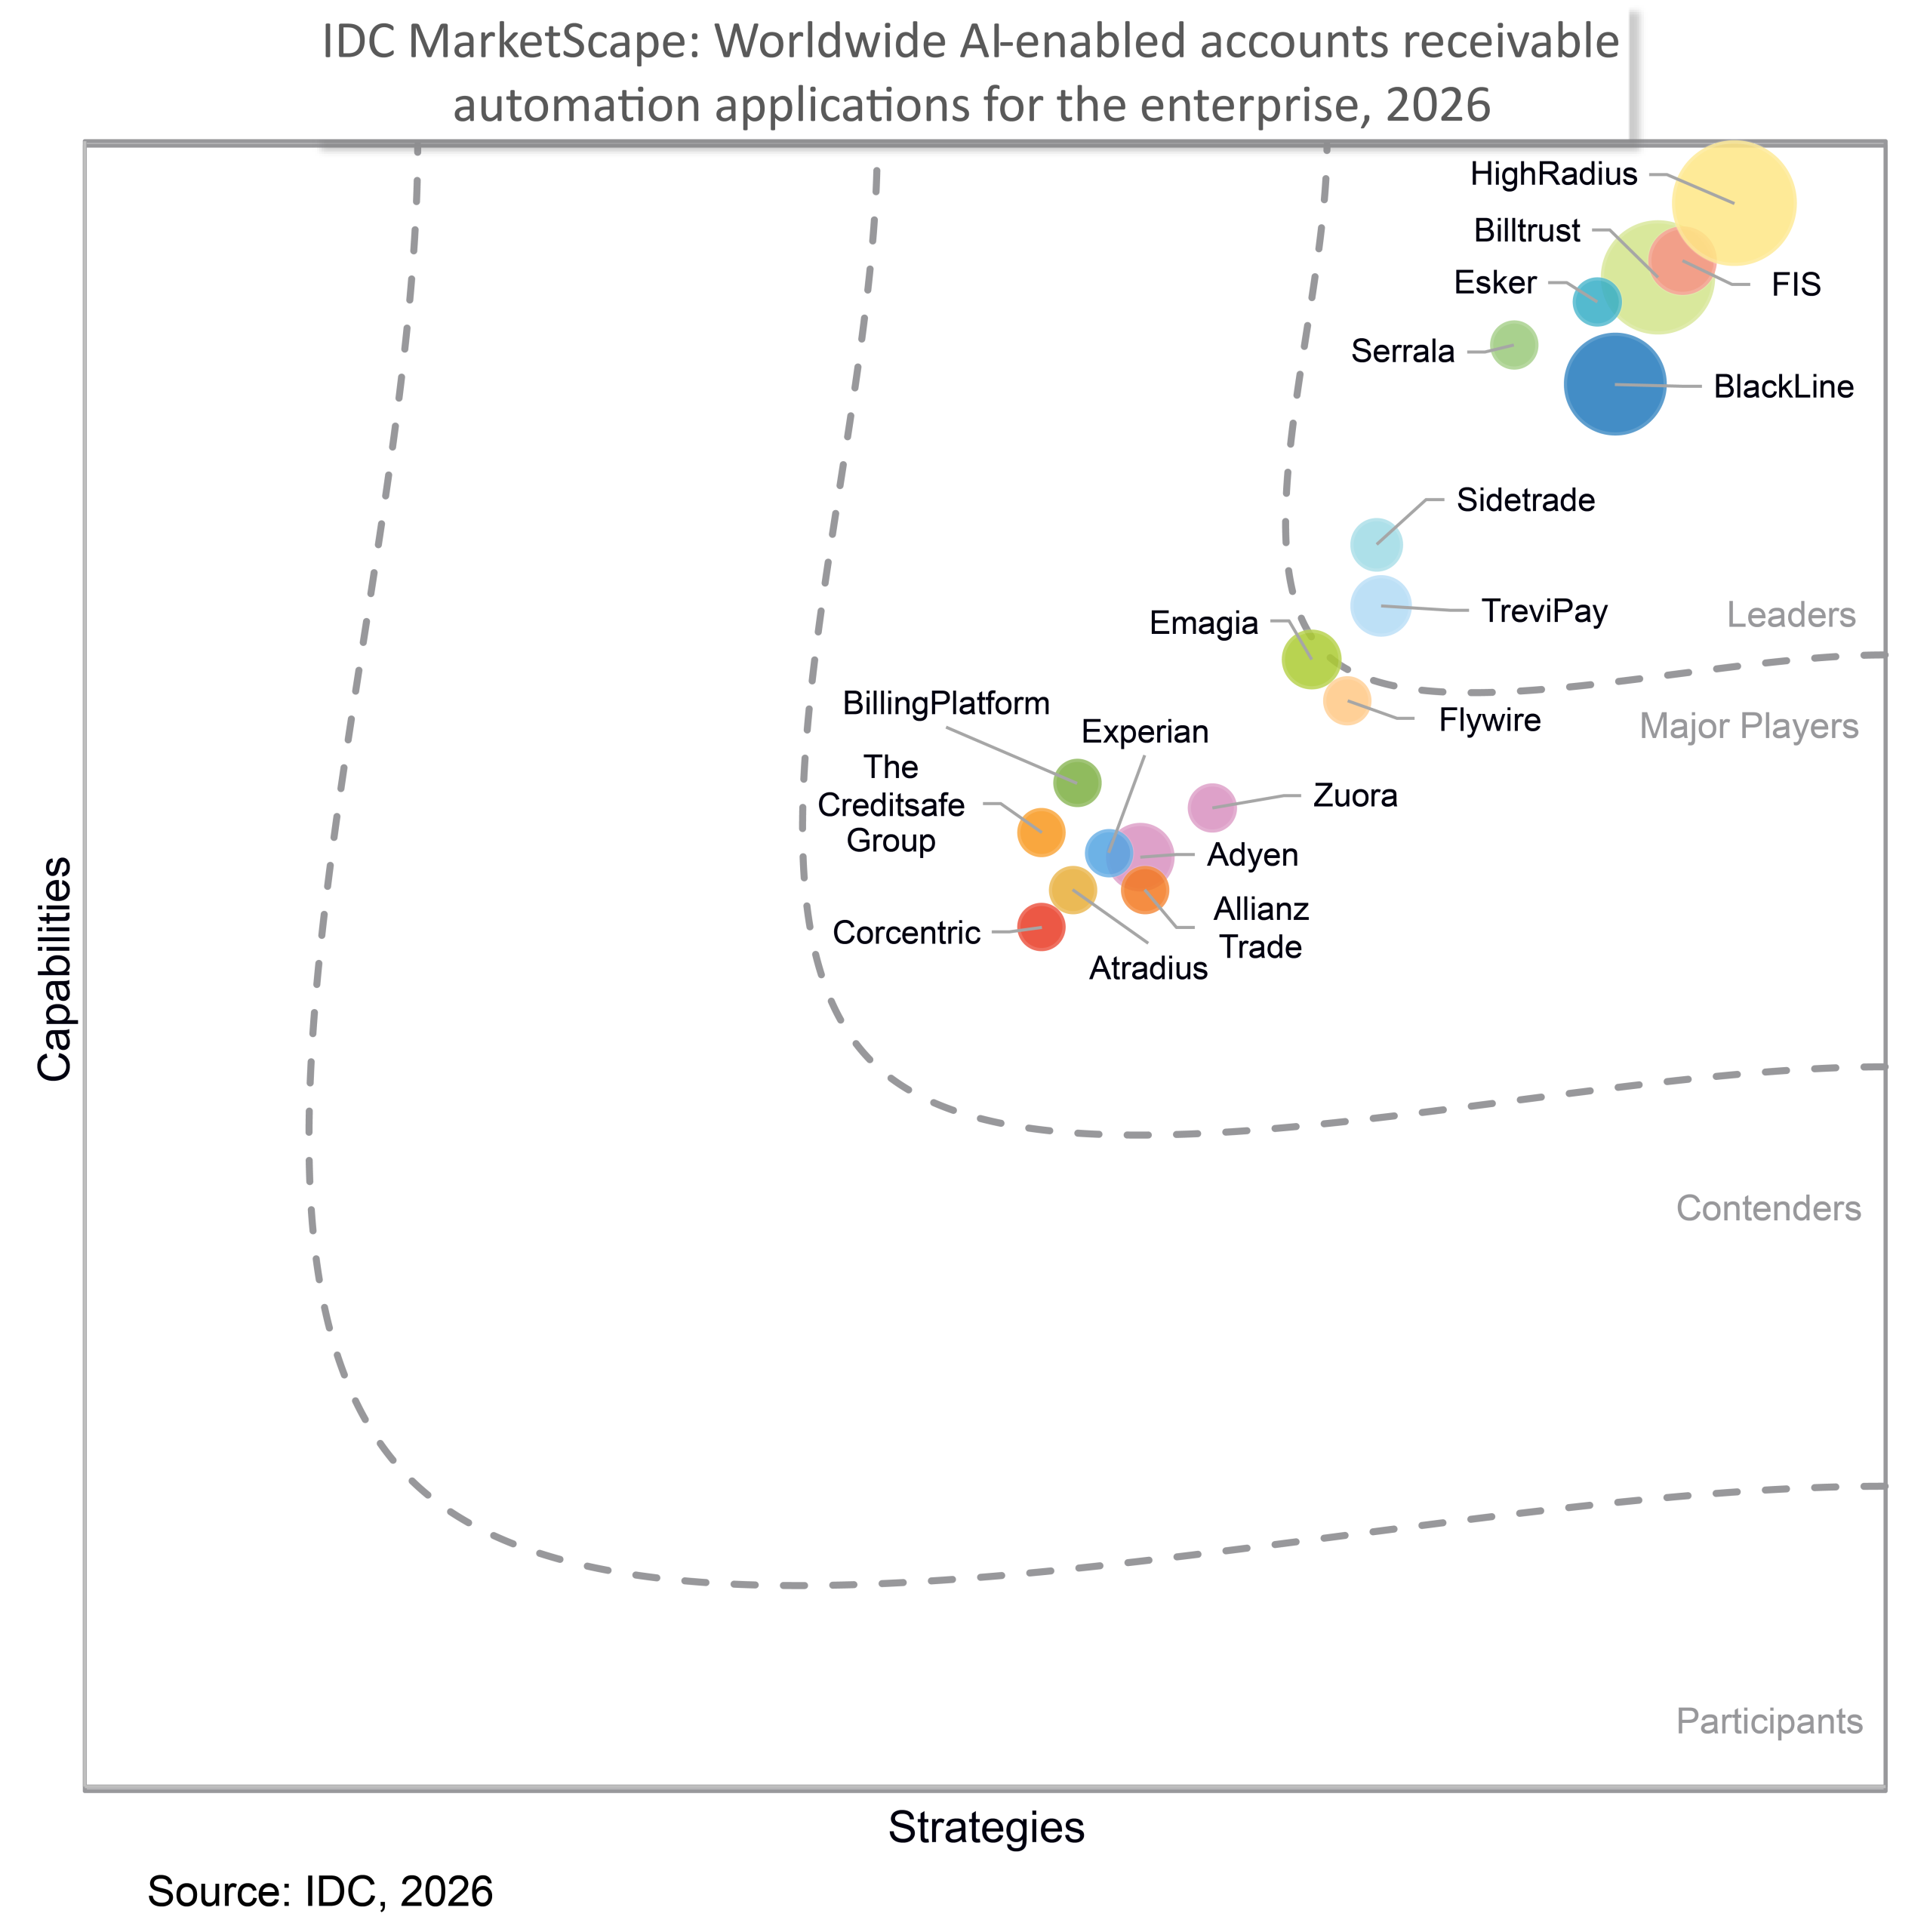
HighRadius recognized as a "Leader" in IDC Marketscape: Worldwide AI-enabled accounts receivable automation applications for the enterprise 2026 vendor assessment
Recognized as a Leader in 2026 Vendor Assessment for unifying credit, collections, cash application, deductions, e-invoicing, and payments on one AI platform to advance enterprise-wide invoice-to-cash transformation.
Forrester Recognizes HighRadius in The AR Invoice Automation Landscape Report, Q1 2023
Forrester acknowledges HighRadius’ significant contribution to the industry, particularly for large enterprises in North America and EMEA, reinforcing its position as the sole vendor that comprehensively meets the complex needs of this segment.